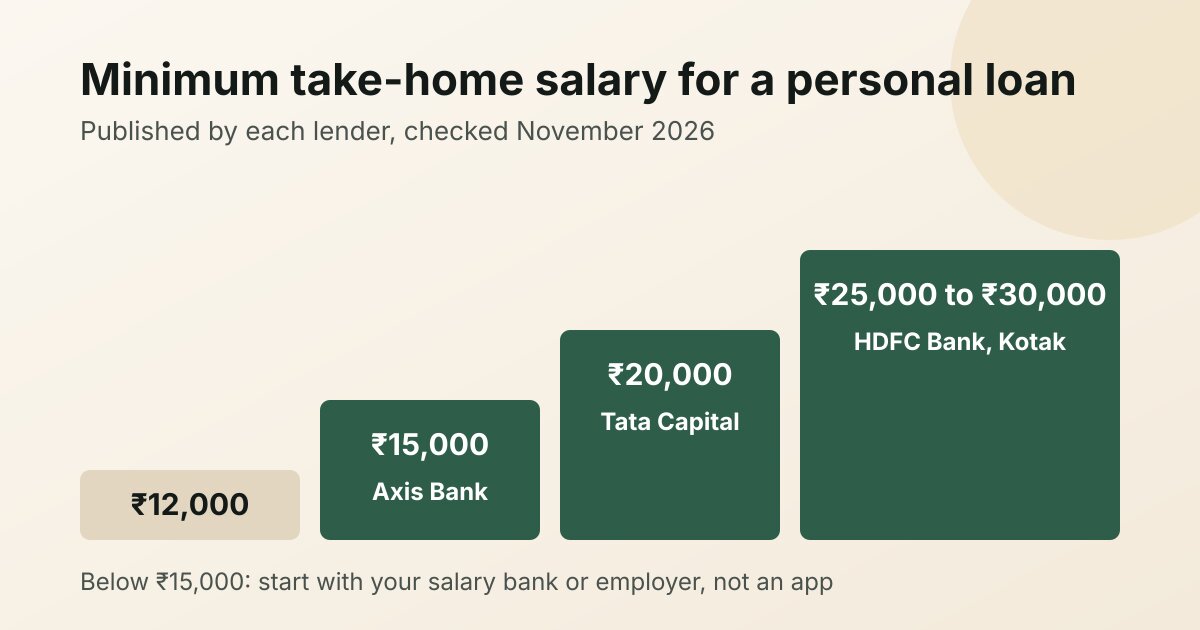
Short answer: most big lenders publish a minimum take-home salary of ₹15,000 to ₹30,000 a month. On lenders' own pages in November 2026: Axis Bank ₹15,000 net a month, Tata Capital ₹20,000, HDFC Bank ₹25,000, and Kotak ₹25,000 (with a Kotak salary account) or ₹30,000. On a ₹15,000 salary, an EMI of about ₹6,000 (40% of pay) supports roughly ₹1.2 lakh to ₹1.3 lakh over 2 years at bank rates. Below ₹15,000, start with your salary bank or employer, not an app.
Lakhs of salaried people take home ₹12,000 to ₹20,000 a month: retail and delivery staff, security guards, office assistants, nurses and new graduates. They are also the people loan apps target hardest. This guide shows where the bank cut-offs sit, how much your salary can carry, and what to do if you fall short.
What minimum salary do lenders ask for?
From lenders' own eligibility pages:
| Lender | Minimum net monthly salary | Other rules on the page | Checked |
|---|---|---|---|
| Axis Bank | ₹15,000 | Statements with salary credits | 20 Nov 2026 |
| Tata Capital | ₹20,000 | Salaried employees | 20 Nov 2026 |
| HDFC Bank | ₹25,000 | 2 years in work, 1 year with the current employer | 20 Nov 2026 |
| Kotak Mahindra Bank | ₹25,000 with a Kotak salary account; ₹30,000 otherwise (₹20,000 for Kotak employees) | Age 21 to 60; at least 1 year of work experience | 22 Nov 2026 |
Three things to notice:
- It is net pay. The figure is what lands in your bank account each month, after PF and tax, not your CTC.
- The minimum is a door, not a promise. Clearing it only means the lender will look at your file. Your existing EMIs, credit history, employer and city still decide approval, amount and rate.
- Your salary bank can be easier. Kotak's own table asks ₹5,000 less from people whose salary is credited to a Kotak account. Many banks make pre-approved offers to their own salary customers.
How much can you borrow on ₹12,000 to ₹20,000?
Lenders cap your total EMIs at a share of take-home pay, called FOIR (fixed obligations to income ratio). Kotak says lenders prefer 40% to 50%; on a small salary, plan on 40%, because rent and food take a bigger bite. The table assumes no other EMIs, at ICICI Bank's published range of 11.60% (its mean rate for July to September 2026) to 16.50% a year:
| Take-home salary | EMI room at 40% | 2 years | 3 years |
|---|---|---|---|
| ₹12,000 | ₹4,800 | about ₹0.98 lakh to ₹1.02 lakh | about ₹1.36 lakh to ₹1.45 lakh |
| ₹15,000 | ₹6,000 | about ₹1.22 lakh to ₹1.28 lakh | about ₹1.69 lakh to ₹1.82 lakh |
| ₹18,000 | ₹7,200 | about ₹1.46 lakh to ₹1.54 lakh | about ₹2.03 lakh to ₹2.18 lakh |
| ₹20,000 | ₹8,000 | about ₹1.63 lakh to ₹1.71 lakh | about ₹2.26 lakh to ₹2.42 lakh |
The higher figure in each range is at 11.60%, the lower at 16.50%. A ₹12,000 salary is below every bank minimum in the first table, so treat that row as the arithmetic only: it shows how little room there is, not an offer you will get.
Every EMI you already pay comes off the top. A ₹2,000 phone or card EMI on an ₹18,000 salary cuts your room from ₹7,200 to ₹5,200. Run your own numbers in the personal loan eligibility calculator, and read FOIR explained for how lenders count it.
A worked example: Sneha, ₹18,000 a month
Sneha is a pharmacy assistant in Pune. Her employer credits ₹18,000 to her bank account each month. She pays ₹2,000 a month on a phone bought on EMI, with 8 months left. She needs ₹1 lakh for her mother's cataract surgery.
Step 1, the bank cut-offs. At ₹18,000 she clears Axis Bank's ₹15,000 minimum. She is below Tata Capital (₹20,000), HDFC Bank and Kotak (₹25,000 or more), so applying there now would only add enquiries to her credit report.
Step 2, her EMI room. 40% of ₹18,000 is ₹7,200. Minus the ₹2,000 phone EMI leaves ₹5,200.
Step 3, the loan that fits.
| ₹1 lakh over | EMI at 11.60% | EMI at 16.50% | Fits in ₹5,200? |
|---|---|---|---|
| 2 years | about ₹4,689 | about ₹4,920 | Yes |
| 3 years | about ₹3,302 | about ₹3,540 | Yes, with room to spare |
Step 4, what she does. She asks her own salary bank whether she has a pre-approved offer, then applies to one lender whose minimum she clears, not five. She picks 2 years if she can manage ₹4,900, because a shorter loan costs less interest. She reads the Key Facts Statement before signing: RBI requires lenders to give one with the all-in annual cost (APR).
What she avoids. Splitting the ₹1 lakh across several instant apps. Payday-style loans are repaid in one go within weeks (Tata Capital describes tenures of 7 to 60 days, some up to 90), so a manageable need turns into large repayments every payday. Our guide on why you should never take a payday loan shows what that costs.
Your salary is below the minimum: what are the options?
In rough order of cost, cheapest first:
- Salary advance from your employer. Many employers advance part of next month's salary at no interest. Ask HR before anything else.
- Your salary bank. Ask whether you have a pre-approved personal loan, or a loan against a fixed deposit if you hold one.
- A smaller amount, a shorter tenure. Asking for ₹50,000 instead of ₹1.5 lakh may bring you inside a lender's limits.
- A co-applicant. A spouse or parent with a higher salary can apply with you where the lender allows it. Both are equally responsible for every EMI.
- Wait and build the proof. Six months of salary credits and on-time EMIs, plus any raise, may take you past the ₹15,000 or ₹20,000 line.
What to avoid: apps that promise "salary loan on ₹10,000" with no checks. Before you download one, check whether the app is linked to an RBI-regulated lender. If you have already borrowed from several, read should I take a loan from one app to repay another? before you take the next one.
Five ways to look stronger to a lender on a small salary
- Get your salary paid into a bank account on a fixed date. Statements are your best income proof, especially without salary slips (what lenders accept instead).
- Close small EMIs first. A ₹1,500 EMI on a ₹15,000 salary takes 10% of your pay and a quarter of your EMI room.
- Keep card use low and pay the full bill, not just the minimum due.
- Check your credit report once a year for free and fix errors before you apply.
- Apply to one or two lenders, not ten. If you are turned down, read personal loan rejected: what to do next.
Already paying several EMIs on a small salary?
If your EMIs take more than half of your pay, a new loan on top will not help. The fix is to bring the total down: one loan that closes several small ones, at a lower rate and a longer tenure. AdvanceCred handles cases with up to 1 payday loan, up to 5 app and personal loans in total, and up to 5 credit cards; the lender still decides approval. Start with the free loan-merge checker or read how to merge multiple EMIs into one.
How AdvanceCred can help
AdvanceCred is a credit advisory and loan intermediation firm in Mumbai. It is not a lender. Our advisors match your salary, employer and existing EMIs against our partner banks' and NBFCs' published rules before you apply, so you do not collect rejections and enquiries. The lender decides approval, amount, rate and tenure.
See personal loans for salaried employees, the ₹25,000 salary guide, browse more in the debt consolidation guides hub, or leave your details below.
Sources
- Axis Bank, Personal loan eligibility and documentation (₹15,000 net monthly income; statements with salary credits), checked 20 November 2026: axis.bank.in
- Tata Capital, Personal loan for salaried (₹20,000 a month minimum), checked 20 November 2026: tatacapital.com
- HDFC Bank, Personal loan eligibility (₹25,000 net a month; 2 years in work, 1 with the current employer), checked 20 November 2026: hdfc.bank.in
- Kotak Mahindra Bank, What is the minimum salary for personal loan in India?, 1 July 2026 (₹25,000 net with a Kotak salary account, ₹30,000 without, ₹20,000 for Kotak employees; age 21 to 60; at least 1 year of work experience), checked 22 November 2026: kotak.bank.in
- Kotak Mahindra Bank, What is FOIR in banking?, 8 September 2026 (lenders prefer 40% to 50%), checked 19 November 2026: kotak.bank.in
- ICICI Bank, Personal loan interest rates (10.25% to 16.50% a year; mean 11.60% for July to September 2026), checked 18 November 2026: icici.bank.in
- Reserve Bank of India, Key Facts Statement for loans and advances, RBI/2024-25/18, 15 April 2024 (KFS with the annual percentage rate for all retail loans from 1 October 2024), checked 20 November 2026: rbi.org.in
- Tata Capital, Payday loans in India: what is a payday loan and how does it work (tenures of 7 to 60 days, some up to 90 days), checked 1 November 2026: tatacapital.com
- Worked example: illustrative profile. Loan amounts and EMIs by the standard reducing-balance formula, calculated by AdvanceCred, 22 November 2026.
This article is general information, not financial advice or an offer of credit. Each lender sets its own income rules and may change them; check the lender's page before you apply.