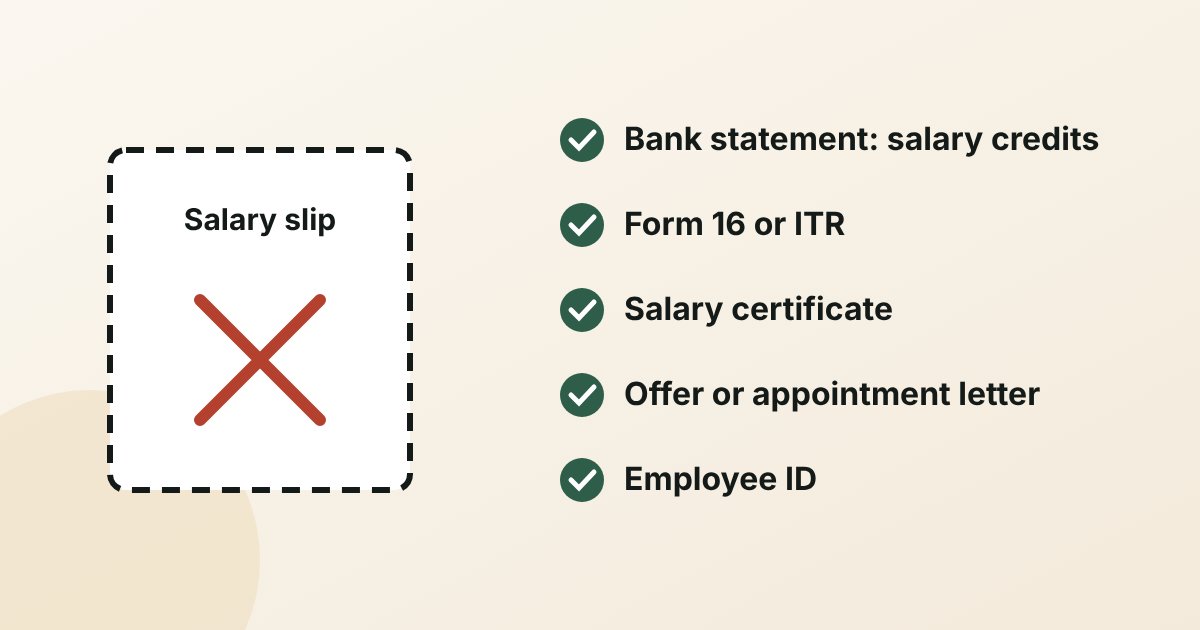
Short answer: often, yes. Lenders need proof of steady income, not a salary slip as such. Many accept bank statements showing regular salary credits, Form 16 or an Income Tax Return (ITR), or a salary certificate from your employer. HDFC Bank's alternate document list accepts a salary certificate with the latest Form 16. If your salary is paid in cash, it is harder: deposit it on a fixed date every month and get a signed employer letter. Never use fake slips.
Lots of salaried people never get a payslip: staff at small shops, clinics and offices, new joiners in their first month, and anyone whose employer pays by bank transfer with no paperwork. A lender's question is simple: is this income real and regular? Here is how to answer it without slips.
What do lenders accept instead of salary slips?
Lenders' own pages, checked 21 November 2026:
| Document | Who lists it | What it proves |
|---|---|---|
| Bank statements with salary credits (3 to 6 months) | IDFC FIRST Bank, Bajaj Finserv; Kotak accepts "recent slips or bank statements"; Axis Bank asks for statements with salary credits | Amount and regularity of salary |
| Form 16 | IDFC FIRST Bank, Bajaj Finserv; HDFC Bank (with a salary certificate) | Annual salary and tax deducted by the employer |
| Income Tax Return (ITR) | IDFC FIRST Bank, Bajaj Finserv, Shriram Finance | Declared income |
| Salary certificate or income certificate | HDFC Bank's alternate list; Bajaj Finserv; IDFC FIRST Bank | Employer confirms your salary |
| Offer letter, employment contract or employer statement | Shriram Finance; IDFC FIRST Bank (employment letter) | That the job exists and what it pays |
| Employee ID | Bajaj Finserv | Employment |
The best substitute is a bank statement. If your employer transfers your salary on roughly the same date every month, three to six months of statements tell a lender almost everything a slip would. Pair it with Form 16 or a salary certificate and most lenders have enough.
Your KYC (PAN plus an identity and address proof such as Aadhaar) is needed either way. Our salaried document checklist lists each lender's full set.
Which situation are you in?
1. Salary comes by bank transfer, but no slips. You are in a good position. Give 6 months of statements, Form 16 if your employer deducts TDS, and a salary certificate on letterhead with your designation, joining date and monthly pay.
2. New job, no slip yet. Your offer or appointment letter plus the first salary credit helps, but many lenders also have a work-experience rule: HDFC Bank asks for 1 year with the current employer and 2 years in work, Kotak for 1 year in the current job. A pre-approved offer from your own bank may be easier until you complete the period.
3. Salary paid in cash. The hardest case. Shriram Finance says a cash salary "may complicate the process" and suggests depositing the cash into your bank account regularly, plus an employer affidavit or statement of your monthly salary and payment date. Start now: three to six months of steady deposits build the proof that slips would have given.
4. No slips and no bank record. Unsecured loans are unlikely. Bajaj Finserv notes some lenders may lend with collateral or a guarantor. Be very careful with apps that say "no documents, no checks": our guide on why you should never take a payday loan shows what they cost.
Minimum income still applies
No slip does not lower the bar. From lenders' pages (checked 20 November 2026): HDFC Bank asks for ₹25,000 net a month, Tata Capital ₹20,000, Axis Bank ₹15,000, and Kotak ₹25,000 (with a Kotak salary account) or ₹30,000. Your statements need to show credits at or above that level.
A worked example: Ravi, ₹32,000 a month, no slips
Ravi works at a small logistics firm in Thane. His employer transfers ₹32,000 to his bank account around the 5th of every month but issues no slips. He has no other loans. He needs about ₹2 lakh.
Step 1, documents. Six months of statements showing six credits of ₹32,000 from his employer, a salary certificate on the firm's letterhead, PAN and Aadhaar. His employer does not deduct TDS, so there is no Form 16; he files an ITR.
Step 2, what he can afford. Lenders compare your EMIs with your income (FOIR). Kotak says lenders prefer 40% to 50%. At 40% of ₹32,000, his EMI room is ₹12,800. At ICICI Bank's published mean rate of 11.60% (July to September 2026):
| EMI | 3 years | 5 years |
|---|---|---|
| ₹12,800 (40% of income) | about ₹3.88 lakh | about ₹5.81 lakh |
| ₹6,400 (20% of income) | about ₹1.94 lakh |
So the ₹2 lakh he needs is about ₹6,605 a month over 3 years, around a fifth of his salary, well inside what lenders accept. A lender that verifies his income only from statements may still offer less or price it higher; that is its call.
Step 3, where to apply. HDFC Bank (₹25,000 minimum) and Tata Capital (₹20,000) are within reach on income. He applies to one or two, not ten: every application adds an enquiry to his credit report.
Our personal loan eligibility calculator does this arithmetic for your own salary and EMIs, and the FOIR guide explains the ratio lenders use.
Do not do this
- Do not buy or "arrange" salary slips. Submitting forged documents to a lender is fraud. It can lead to the loan being recalled and a criminal complaint, and it follows you on your credit history.
- Do not borrow from an app because a bank asked for documents. Gather the alternatives above first.
- Do not apply everywhere at once. Many enquiries in a short time make you look credit-hungry. If you were turned down, read personal loan rejected: what to do next.
- Do not sign without the Key Facts Statement. RBI requires lenders to give one for every retail loan, with the all-in annual cost (APR).
How AdvanceCred can help
AdvanceCred is a credit advisory and loan intermediation firm in Mumbai. It is not a lender. Our advisors check which of our partner banks and NBFCs accept your kind of income proof before you apply, so you do not collect rejections and enquiries. The lender decides approval, amount, rate and tenure.
See personal loans for salaried employees or personal loans, browse more in the debt consolidation guides hub, or leave your details below.
Sources
- IDFC FIRST Bank, Personal loan without salary slip, 6 August 2026 (bank statements, ITR, income certificate, Form 16, employment letter; "A higher rate is not automatic"), checked 21 November 2026: idfcfirst.bank.in
- Bajaj Finserv, Personal loan without salary slip, 9 June 2026 (income certificate, bank statements, ITR or Form 16; employee ID; cash earners need other proof; collateral or guarantor; pre-approved offers), checked 21 November 2026: bajajfinserv.in
- Shriram Finance, How to get a personal loan against a cash salary in India, modified 7 July 2025 (cash salary "may complicate the process"; regular deposits; offer letter, ITR, employer affidavit or statement), checked 21 November 2026: shriramfinance.in
- HDFC Bank, Personal loan documentation, alternate list (2 salary slips or salary certificate with the latest Form 16; 3 months of statements), checked 20 November 2026: hdfc.bank.in; eligibility (₹25,000 net a month; 2 years in work, 1 with current employer): hdfc.bank.in
- Axis Bank, Personal loan eligibility and documentation (₹15,000 net a month; statements with salary credits), checked 20 November 2026: axis.bank.in
- Kotak Mahindra Bank, Personal loan for salaried (recent slips or bank statements; ₹25,000 or ₹30,000 minimum; 1 year in current job), checked 20 November 2026: kotak.bank.in
- Tata Capital, Personal loan for salaried (₹20,000 a month minimum), checked 20 November 2026: tatacapital.com
- Kotak Mahindra Bank, What is FOIR in banking?, 8 September 2026 (lenders prefer 40% to 50%), checked 19 November 2026: kotak.bank.in
- ICICI Bank, Personal loan interest rates (mean 11.60% for July to September 2026), checked 18 November 2026: icici.bank.in
- Reserve Bank of India, Key Facts Statement for loans and advances, RBI/2024-25/18, 15 April 2024 (all new retail and MSME term loans from 1 October 2024; APR), checked 20 November 2026: rbi.org.in
- Worked example: illustrative profile; loan amounts and EMI by the standard reducing-balance formula, calculated by AdvanceCred, 21 November 2026.
This article is general information, not financial advice or an offer of credit. Each lender sets its own document rules; check with the lender before you apply.