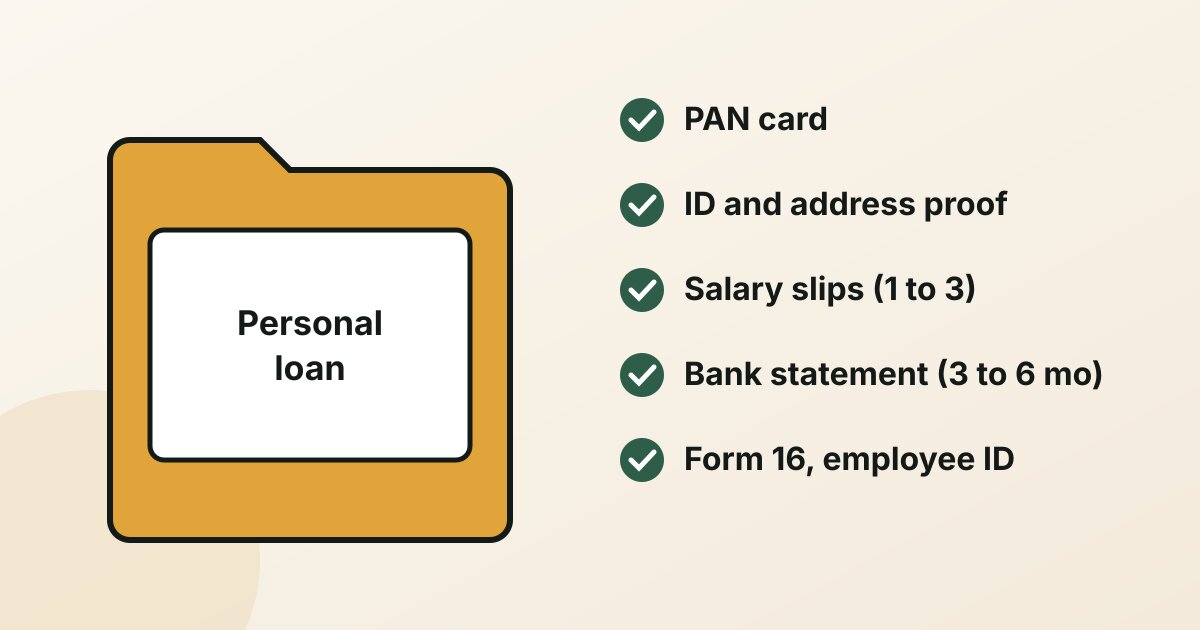
Short answer: for a salaried personal loan, most banks and NBFCs ask for PAN, one identity and address proof (Aadhaar, passport, driving licence or voter ID), your latest 1 to 3 salary slips, 3 to 6 months of salary-account bank statements, and sometimes Form 16 and an employee ID. Existing customers with a pre-approved offer may need little or no paperwork. Keep one complete set ready and apply to one or two lenders, not ten.
Missing or mismatched documents are one of the simplest reasons a loan gets delayed or declined. This checklist is built from what seven lenders publish on their own pages, checked on 20 November 2026.
The salaried personal loan document checklist
| Document | Why the lender wants it | Keep ready |
|---|---|---|
| PAN card | Required under RBI's KYC rules (or Form 60) | PAN card or e-PAN |
| Identity and address proof | KYC | One of: Aadhaar, passport, driving licence, voter ID, NREGA job card, NPR letter |
| Salary slips | Income proof | Latest 3 months (some lenders need only 1 or 2) |
| Bank statement | Salary credits and existing EMIs | Last 6 months of the account your salary is paid into |
| Form 16 | Annual income and tax | Last 2 years (Tata Capital asks for 2; HDFC Bank's alternate list asks for the latest) |
| Employment proof | Job and tenure | Employee ID card, offer letter or a continuous-employment letter |
| Photograph | Application form | Recent passport-size photo, or a live photo in an app |
If your address on Aadhaar or your ID is old, update it before applying. Lenders compare the name, date of birth and address across your documents and your credit report.
What each lender asks for
Documents, from each lender's own page (checked 20 November 2026):
| Lender | Salary slips and statements | Other documents |
|---|---|---|
| HDFC Bank | Latest 3 slips (an alternate list says 2 plus the latest Form 16); last 3 months of statements | ID and address: passport, voter ID, driving licence or Aadhaar |
| ICICI Bank | Last 1 month of slips; latest 3 months of statements | Passport-size photos; Aadhaar and PAN details mandatory |
| Axis Bank | Latest 2 months of slips and of statements with salary credits | One year employment proof (waived if the slip shows the joining date and over a year's service) |
| Kotak Mahindra Bank | Recent slips or bank statements | Proof of employment |
| Bajaj Finance | Last 3 months of slips and of statements | PAN, a live photo, employee ID |
| Tata Capital | Latest 3 months of slips; 3 to 6 months of statements | Form 16 for 2 years; one-year continuous employment certificate |
Minimum income and age, from the same lenders:
| Lender | Minimum income | Age and work |
|---|---|---|
| HDFC Bank | ₹25,000 net a month | 21 to 60; 2 years in work, 1 with current employer |
| ICICI Bank | Not stated on the page | 20 to 58 |
| Axis Bank | ₹15,000 net a month | 21+, up to 60 at maturity |
| Kotak Mahindra Bank | ₹25,000 (Kotak salary account) or ₹30,000 | 21 to 60; 1 year in current job |
| Bajaj Finance | Not stated on the page | 21 to 80 at end of tenure; CIBIL 650+ |
| Tata Capital | ₹20,000 a month | 21 to 58; CIBIL 725+ preferred |
SBI's Xpress Credit page lists a minimum net monthly income of ₹5,000, a salary account with SBI and an EMI-to-income ratio of no more than 50%, but its document list could not be confirmed on SBI's own site on 20 November 2026, so it is left out of the table.
Notice that even one lender can publish two versions (HDFC Bank, Axis Bank and Tata Capital each show two salary-slip counts on different pages). Three slips and six months of statements covers every lender above.
A worked example: which lenders fit, and what to send
Priya works at a private company in Pune. She takes home ₹28,000 a month, has been with her employer for 3 years, and pays one ₹4,500 EMI on a phone loan.
Step 1, minimum income. On the published minimums, she meets Axis Bank (₹15,000 net), Tata Capital (₹20,000) and HDFC Bank (₹25,000 net, with at least 2 years in work and 1 with her current employer). She does not meet Kotak's ₹30,000 for people without a Kotak salary account. Applying there first would only add an enquiry to her report.
Step 2, how much room her salary has. Lenders work out how much of your income already goes to EMIs (FOIR). Her existing EMI is ₹4,500 of ₹28,000, about 16%. If a lender allows total EMIs up to 40% of take-home pay, that is ₹11,200 a month, leaving about ₹6,700 for a new EMI. At ICICI Bank's published mean rate of 11.60% (July to September 2026), ₹6,700 a month over 3 years supports a loan of roughly ₹2 lakh. Our FOIR guide shows the full method, and the eligibility calculator does the arithmetic for you.
Step 3, one document set. PAN, Aadhaar, her last 3 salary slips, 6 months of salary-account statements (they will show the ₹4,500 EMI, which is fine because she declares it), Form 16 for the last 2 years, her employee ID and a photo. That one folder works for all three lenders that fit.
Step 4, apply to one or two. Every application adds an enquiry. Choose the lender whose criteria fit best, and wait for its answer before trying the next.
Can you get a personal loan with fewer documents?
- Pre-approved offers. HDFC Bank says KYC-compliant customers can get a personal loan with no documentation. ICICI Bank offers pre-approved loans to eligible existing customers without physical documents, using bank records, net banking or Account Aggregator data. Axis Bank says pre-approved and pre-qualified customers need minimal or no additional documents. Bajaj Finance says even pre-approved loans may need minimal documents.
- Digital KYC. RBI's KYC rules allow Aadhaar e-KYC and video KYC (V-CIP), which RBI treats on par with a face-to-face check, so you may not need to visit a branch.
- Without salary slips. Some lenders accept a salary certificate or bank statements showing regular salary credits. Ask the lender directly; do not use an agent who offers to "arrange" slips.
Mistakes that delay a loan
- Name or date-of-birth mismatch between PAN, Aadhaar and your salary slip. Fix it at the source first.
- Salary paid in cash or to a different account from the statements you share. Share the account the salary actually comes into.
- Hiding existing loans. The bank statement and your credit report show them anyway. Declared EMIs are better than discovered ones.
- Sharing documents with unverified apps or agents. RBI's Digital Lending Directions require data collection to be need-based and with your explicit consent, and bar lending apps from accessing your contacts or call logs. Check who the lender is before you upload anything. Our guide on checking whether a loan app is RBI-registered explains how.
- Applying everywhere after one rejection. Find the reason first; see personal loan rejected: what to do next.
Before you sign, read the Key Facts Statement. Since 1 October 2024, RBI requires lenders to give every retail term loan borrower a KFS showing the annual percentage rate (interest plus all charges) before the loan contract is signed.
How AdvanceCred can help
AdvanceCred is a credit advisory and loan intermediation firm in Mumbai. It is not a lender. An advisor can tell you which partner banks and NBFCs fit your salary, employer and existing EMIs, what each one will ask for, and help you send one complete set, so you do not collect enquiries from lenders that were never going to fit. If you already pay several EMIs, ask about merging them into one first: AdvanceCred works on cases with up to 1 payday loan, up to 5 app and personal loans in total and up to 5 credit cards. The lender decides approval, amount, rate and tenure.
See personal loan rates and eligibility or the instant salary loan for salaried employees page, browse more guides in the debt consolidation guides hub, or leave your details below.
Sources
- HDFC Bank, Personal loan documentation (latest 3 salary slips; no documentation for KYC-compliant customers), checked 20 November 2026: hdfc.bank.in; alternate list (2 slips or salary certificate with latest Form 16; 3 months of statements): hdfc.bank.in; eligibility (₹25,000 net a month, 21 to 60 years, work experience): hdfc.bank.in
- ICICI Bank, Personal loan documents (OVD list, 3 months of statements, 1 month of salary slips, photos, Aadhaar and PAN details mandatory, pre-approved loans without physical documents), checked 20 November 2026: icici.bank.in; salaried page (20 to 58 years): icici.bank.in
- ICICI Bank, Personal loan interest rates (mean 11.60% for July to September 2026), checked 18 November 2026: icici.bank.in
- Axis Bank, Personal loan eligibility and documentation (₹15,000 net a month; 2 months of slips and statements; employment proof; pre-approved route), checked 20 November 2026: axis.bank.in
- Kotak Mahindra Bank, Personal loan for salaried (₹25,000 or ₹30,000 minimum salary; 21 to 60 years; 1 year in current job; documents), checked 20 November 2026: kotak.bank.in
- Bajaj Finance, Personal loan eligibility and documents (3 months of slips and statements; PAN and live photo; 21 to 80 years; CIBIL 650+), checked 20 November 2026: bajajfinserv.in
- Tata Capital, Personal loan documents required (last updated 30 October 2026) and personal loan for salaried (₹20,000 a month; 21 to 58 years; CIBIL 725+ preferred), checked 20 November 2026: tatacapital.com, tatacapital.com
- SBI, Xpress Credit (minimum net monthly income ₹5,000; salary account with SBI; EMI/NMI up to 50%), checked 20 November 2026: sbi.co.in
- Reserve Bank of India, KYC FAQs (officially valid documents; PAN or Form 60; Aadhaar voluntary; e-KYC; V-CIP on par with face-to-face), checked 20 November 2026: rbi.org.in
- Reserve Bank of India, Key Facts Statement for loans and advances, RBI/2024-25/18, 15 April 2024 (all new retail and MSME term loans from 1 October 2024; APR), checked 20 November 2026: rbi.org.in
- Reserve Bank of India, Digital Lending Directions, 2025, RBI/2025-26/36, 8 May 2025 (para 12: need-based data collection with explicit consent; no access to contacts or call logs), checked 20 November 2026: rbi.org.in
- Worked example: illustrative profile; EMI by the standard reducing-balance formula, calculated by AdvanceCred, 20 November 2026.