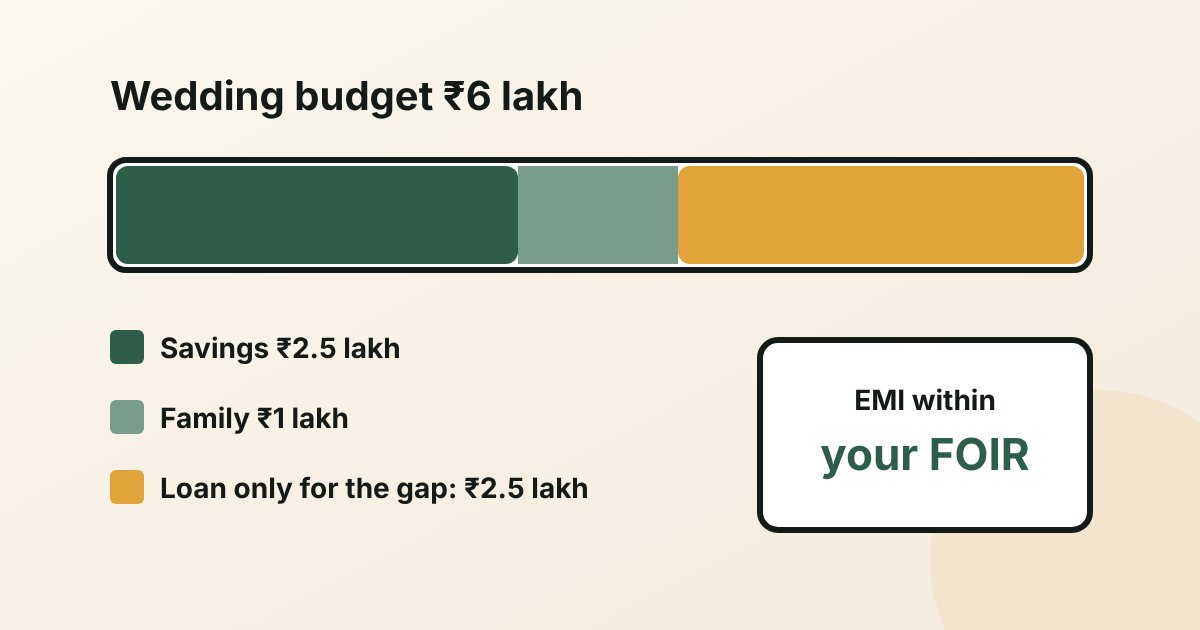
Short answer: borrow only the gap between the wedding budget and what savings and family cover, and keep all your EMIs within about 40% of take-home pay, the lower end of the 40% to 50% that lenders prefer. On a ₹50,000 salary with a ₹6,000 EMI already running, ₹2.5 lakh over 3 years at about 11% costs about ₹8,200 a month and ₹45,000 in interest. A bank or NBFC personal loan costs far less than card debt or app loans.
Wedding costs arrive in a rush: venue advances, jewellery, catering, travel. Most of it is due months before the day. That is why many families look at a personal loan, and why it is easy to borrow more than the salary can carry once the celebrations are over.
How much can you borrow, and how much should you?
Lenders decide on FOIR: your total monthly EMIs (plus card dues) as a share of income. Kotak says lenders prefer 40% to 50%. The higher figure is the most a lender may offer, not a target.
A safer way to set the amount:
- Write the full budget with every major line: venue, food, clothes and jewellery, travel, gifts.
- Subtract what is already there: savings you can spare without emptying your emergency fund, and what family members are contributing.
- Borrow only the gap, and check its EMI keeps your total EMIs at or under 40% of take-home pay.
- Leave room for life after the wedding. Rent, a new home or a move can raise your monthly costs right when EMIs start.
A worked example: ₹6 lakh wedding on a ₹50,000 salary
Ankit takes home ₹50,000 a month and pays a ₹6,000 bike loan EMI. The wedding budget is ₹6 lakh. He has ₹2.5 lakh saved for it and his family is putting in ₹1 lakh.
The gap is ₹2.5 lakh.
The lender's ceiling: 40% of ₹50,000 is ₹20,000 of total EMIs. Less his bike EMI, that leaves ₹14,000 a month, which supports about ₹4.2 lakh over 3 years at 11.60% (ICICI Bank's published mean rate, July to September 2026). He could be offered that much. He does not need it.
The cost of ₹2.5 lakh, at Tata Capital's starting rate of 10.99% and ICICI Bank's mean of 11.60%:
| Tenure | EMI at 10.99% | Total interest | EMI at 11.60% | Total interest |
|---|---|---|---|---|
| 3 years | ₹8,183 | about ₹44,600 | ₹8,256 | about ₹47,200 |
| 5 years | ₹5,434 | about ₹76,000 | ₹5,511 | about ₹80,600 |
Ankit picks 3 years. His total EMIs become about ₹14,250, or 28.5% of take-home pay, with room to spare. The 5-year option would have cost him about ₹31,000 more in interest.
Fees: at Tata Capital's maximum processing fee of 5% plus 18% GST, ₹2.5 lakh would carry up to ₹14,750 in fees. Fees vary by lender and profile, so compare the Key Facts Statement, which shows the all-in annual cost (APR).
Gift money: if the couple receive cash gifts, prepaying part of the loan shortens it. Tata Capital allows up to 25% of the disbursed amount free, which on ₹2.5 lakh is ₹62,500.
Use our personal loan eligibility calculator to run your own numbers, and the FOIR guide explains the ratio in detail.
What lenders ask for
A marriage loan is an ordinary personal loan used for a wedding. Tata Capital's marriage loan page (updated 17 November 2026) shows what to expect:
| Tata Capital marriage loan | |
|---|---|
| Amount | ₹40,000 to ₹35 lakh |
| Tenure | Up to 6 years |
| Rate | From 10.99% a year; final rate on assessment |
| Processing fee | Up to 5% plus taxes |
| Salaried eligibility | 21 to 58 years; ₹20,000 a month minimum; CIBIL 725+ preferred |
| Documents | PAN, KYC, latest 3 salary slips, Form 16 for 2 years, 3 to 6 months of salary-account statements |
| Prepayment | Up to 25% of the disbursed amount free; above that, and on foreclosure, 6.5% in the first 12 months and 4.5% after |
Other banks have similar rules; our salaried document checklist compares HDFC Bank, ICICI Bank, Axis Bank, Kotak, Bajaj Finance and Tata Capital. Apply two to three months before the big payments fall due, so you are not deciding in a hurry.
Personal loan, credit card or app loan?
| Option | Cost | When it works |
|---|---|---|
| Savings and family | Nothing in interest | Always first |
| Personal loan from a bank or NBFC | From about 11% a year (lender pages above) | The gap, over the shortest tenure you can carry |
| Credit card | Up to 3.75% a month plus 18% GST on unpaid balances (Federal Bank's terms) | Only if you pay the full bill by the due date |
| Payday or instant app loans | Usually the costliest | Avoid |
On a card, carrying ₹1 lakh and paying ₹10,000 a month takes about 14 months and costs about ₹35,000 in interest and GST. A 12-month personal loan of ₹1 lakh at 11.60% costs about ₹6,400 in interest. Our article on the credit card minimum due trap shows the arithmetic, and why you should never take a payday loan covers the apps.
Already paying several EMIs?
If a wedding loan would push your EMIs past half your salary, do not add a sixth loan to five. Lenders may decline it, and if they approve it, the month-end squeeze often ends in an app loan. A better order:
- Check whether merging your current loans into one at a lower rate frees enough room first. Our page on personal loans when you already have loans compares a second loan, a top-up and one consolidation loan.
- Then borrow only the gap the new EMI room allows.
How AdvanceCred can help
AdvanceCred is a credit advisory and loan intermediation firm in Mumbai. It is not a lender. Our advisors compare personal loan offers from partner banks and NBFCs and check what your salary can carry before you apply. If you already have several loans, we work on cases with up to 1 payday loan, up to 5 app and personal loans in total and up to 5 credit cards. The lender decides approval, amount, rate and tenure.
See personal loans, check your numbers with the loan-merge checker, browse the debt consolidation guides hub, or leave your details below.
Sources
- Tata Capital, Personal loan for marriage, last updated 17 November 2026 (₹40,000 to ₹35 lakh; up to 6 years; from 10.99% a year; processing up to 5% plus taxes; salaried 21 to 58, ₹20,000 a month, CIBIL 725+ preferred; documents; 25% part-prepayment free, 6.5% and 4.5% charges; no tax benefit), checked 21 November 2026: tatacapital.com
- Kotak Mahindra Bank, What is FOIR in banking?, 8 September 2026 (lenders prefer 40% to 50%), checked 19 November 2026: kotak.bank.in
- ICICI Bank, Personal loan interest rates (mean 11.60% for July to September 2026), checked 18 November 2026: icici.bank.in
- Federal Bank, Credit cards Most Important Terms and Conditions (up to 3.75% a month, 45% a year), checked 4 November 2026: federal.bank.in; IndusInd Bank, GST at 18% on card interest, checked 4 November 2026: indusind.bank.in
- Reserve Bank of India, Key Facts Statement for loans and advances, RBI/2024-25/18, 15 April 2024 (APR disclosed for retail loans from 1 October 2024), checked 20 November 2026: rbi.org.in
- Worked example: illustrative budget and salary; EMI and interest by the standard reducing-balance formula; card cost by a simplified monthly calculation (banks charge interest daily), calculated by AdvanceCred, 21 November 2026.
This article is general information, not financial advice or an offer of credit. Rates and fees change; check the lender's current Key Facts Statement before you borrow.