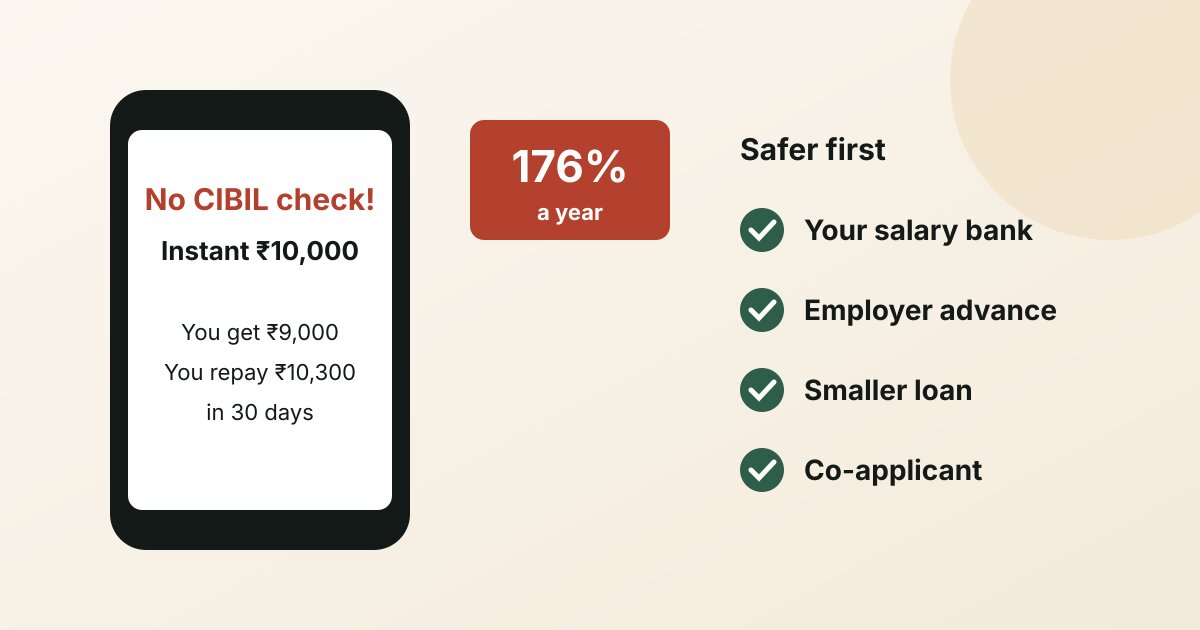
Short answer: a regulated bank or NBFC almost always checks your credit history before it lends. RBI has set no minimum CIBIL score, and a first-time borrower should not be turned down only for having no history, but lenders still look at repayment history, settlements and write-offs. Ads for "no CIBIL check" loans usually mean one of three things: a small, short loan priced for high risk, a secured loan (gold or a deposit), or an app not tied to any regulated lender. On a ₹10,000, 30-day app loan with a ₹1,000 fee and ₹300 interest, the yearly cost is about 176%.
People search for these loans for two very different reasons: they have no credit history yet, or their score has already fallen after missed EMIs. The right next step is different for each, and neither needs an app that skips the checks.
What does "no CIBIL check" usually mean?
| What the ad says | What is usually happening | What to watch |
|---|---|---|
| "No CIBIL needed, first loan" | A lender accepts new-to-credit borrowers and judges you on income and bank statements instead of a score | Fine if the lender is regulated; amounts start small |
| "Low CIBIL OK" | The lender still pulls your report but accepts more risk, so it charges more and lends less | Compare the APR in the Key Facts Statement |
| "Instant cash, no checks" (gold, FD) | A secured loan: the gold or deposit is the lender's safety | You lose the gold or deposit if you do not repay |
| "No documents, no CIBIL, money in 5 minutes" | Often an app with no regulated lender behind it, or one that hides fees in the amount it pays out | Red flags below; do not download |
Bajaj Finserv's own explainer puts it plainly: "no credit check" does not always mean no eligibility assessment, and such loans "may involve higher borrowing costs or less favourable repayment terms". Tata Capital lists higher interest rates and refusals as the usual outcome when there is no score.
What the rules say
- No RBI minimum score. On 25 August 2025, Business Standard reported the Minister of State for Finance telling the Lok Sabha that RBI has not prescribed a minimum credit score, and that applications from first-time borrowers should not be rejected only because they have no credit history. Lenders still check repayment history, delays, restructured or settled loans and write-offs. The score is "only one of several factors".
- Lenders report what you borrow. RBI's Digital Lending Directions, 2025 require regulated lenders to report loans made through digital lending apps to credit bureaus. A loan from a real lender's app shows on your report whether or not it checked your score first, so missing an EMI on a "no CIBIL" loan still hurts your score.
- You must see the full cost first. RBI's Key Facts Statement rules (15 April 2024) require every retail loan to come with a KFS showing the annual percentage rate (APR), which includes fees, before you sign.
- Money goes to your own account. Under the 2025 directions, the loan is paid into your bank account and repaid to the lender directly, not through a third party's account; apps must not access your contacts, call logs or photos; and you get a cooling-off period of at least one day to exit by repaying the principal.
A worked example: what a "no CIBIL check" app loan costs
Arjun earns ₹22,000 a month. His score fell after two late card payments, his bank turned him down, and an app offers ₹10,000 for 30 days, "no CIBIL check". This is an illustrative offer; read your own KFS for real figures.
The offer: a ₹1,000 processing fee taken out before payout, and ₹300 interest. He receives ₹9,000 and must repay ₹10,300 after 30 days.
The yearly cost: he pays ₹1,300 to use ₹9,000 for 30 days, which is 14.4% for a month. Over a year that is about 176% APR (₹1,300 ÷ ₹9,000 × 365 ÷ 30).
Compared with a bank loan: the same ₹10,000 from a bank at 16.50% a year (the top of ICICI Bank's published range) over 12 months costs about ₹916 in interest for the whole year, plus a processing fee of up to 2% (about ₹236 with GST). That is less than the app charges for one month.
The real trap is month two. If ₹10,300 is too much to repay on payday, the next app loan pays the first one, and another ₹1,300 goes in fees. Three rounds cost ₹3,900 for the use of ₹9,000. Our guide on taking a loan from one app to repay another shows how fast this grows.
Red flags: do not borrow if you see these
- The app does not name the bank or NBFC that is lending.
- The lender does not list the app on RBI's public directory of digital lending apps (how to check).
- No Key Facts Statement, or no APR in it.
- It asks for access to your contacts, photos or files.
- Money comes from, or must be repaid to, someone's personal account or UPI ID.
- Pressure to decide in minutes, or threats when you ask questions.
Report such apps on RBI's Sachet portal, and any harassment or fraud on the 1930 cybercrime helpline or cybercrime.gov.in.
Safer options if you have no credit history
- Your salary bank. It already sees your income every month. Ask for a small personal loan or a pre-approved offer.
- A card or loan against a fixed deposit. Many banks issue a first credit card against a fixed deposit. Use a little of the limit and pay the full bill each month.
- A small first loan, repaid on time. Tata Capital suggests asking for a smaller amount, showing income proof and a guarantor; six to twelve months of on-time EMIs build the history the next lender wants.
- A co-applicant with a good record, where the lender allows it. Both of you are responsible for every EMI.
Safer options if your score has already fallen
- Read your report first. Find out exactly what is pulling it down (how to read your CIBIL report) and dispute any mistakes.
- Clear what is overdue now. A current overdue amount is the most common reason for a rejection.
- Do not add more short loans. Each new app loan adds an enquiry and another repayment on payday.
- Replace several costly loans with one. If you are still paying, one personal loan at a bank rate can close several app loans and card balances. AdvanceCred handles cases with up to 1 payday loan, up to 5 app and personal loans in total, and up to 5 credit cards; the lender still decides approval. See payday and app loan consolidation, debt consolidation with a low CIBIL score, or try the free loan-merge checker.
Also read why you should never take a payday loan.
How AdvanceCred can help
AdvanceCred is a credit advisory and loan intermediation firm in Mumbai. It is not a lender, and it never offers loans that skip the lender's checks. Our advisors look at your report and income with you and match you only to regulated partner banks and NBFCs whose rules you meet. The lender decides approval, amount, rate and tenure.
Browse more in the debt consolidation guides hub, or leave your details below.
Sources
- Business Standard, CIBIL score not mandatory: govt tells banks not to reject first-time loans, 25 August 2025 (Minister of State for Finance Pankaj Chaudhary in the Lok Sabha: RBI has not prescribed a minimum score; first-time borrowers not to be rejected only for no credit history; lenders still check repayment history, settlements and write-offs), checked 22 November 2026: business-standard.com
- Reserve Bank of India, Reserve Bank of India (Digital Lending) Directions, 2025, 8 May 2025 (para 9 disbursal to the borrower's account and repayment to the lender; para 10(i) cooling-off period of at least one day; para 12(i) no access to contacts, call logs, files and media; para 16(i) reporting to credit bureaus; para 17 public listing of DLAs), checked 19 November 2026: rbi.org.in
- Reserve Bank of India, press release on the Digital Lending Directions, 2025 and the public directory of DLAs, 8 May 2025, checked 19 November 2026: rbi.org.in
- Reserve Bank of India, Key Facts Statement for loans and advances, RBI/2024-25/18, 15 April 2024 (KFS with APR for all retail loans from 1 October 2024), checked 20 November 2026: rbi.org.in
- OMM Com News (IANS), Govt, RBI strengthen consumer protection measures against fraudulent loan apps, 17 March 2026 (Sachet portal; National Cybercrime Reporting Portal and 1930 helpline), checked 19 November 2026: ommcomnews.com
- Bajaj Finserv, What are no credit check loans? (last reviewed September 2026; "does not always mean no eligibility assessment"; may involve higher costs or less favourable terms), checked 22 November 2026: bajajfinserv.in
- Tata Capital, How to get an instant loan without a CIBIL score, modified 2 November 2026 (guarantor, smaller amount, income proof, collateral; higher interest rates or refusal), checked 22 November 2026: tatacapital.com
- ICICI Bank, Personal loan interest rates (10.25% to 16.50% a year; processing fee up to 2% plus taxes), checked 18 November 2026: icici.bank.in
- Worked example: illustrative offer and profile. APR as simple annualised cost on the amount received; bank interest by the standard reducing-balance formula; calculated by AdvanceCred, 22 November 2026.
This article is general information, not financial advice or an offer of credit. Check any lender's Key Facts Statement before you borrow.