Short answer: most fixed-rate personal loans in India charge 2% to 6.5% of the outstanding principal, plus GST, to close early, and many lenders cut or drop the charge after 24 or 36 EMIs. RBI's 2025 directions ban pre-payment charges only on floating-rate loans to individuals, from 1 January 2026; most personal loans are fixed-rate, so the lender's policy still applies. Closing early usually still saves money when more than a year of EMIs is left. Work out the interest you save against the charge before you pay.
A bonus, a maturing deposit or a cheaper loan offer all raise the same question: close the loan now, part-pay it, or keep paying? The answer is arithmetic, and it starts with your lender's charges.
Personal loan foreclosure charges by lender
All figures from each lender's own fees page, checked 20 November 2026. "Outstanding" means principal outstanding. Check your own sanction letter and Key Facts Statement, because the terms you signed are the ones that apply.
| Lender | Foreclosure charge | Part-payment | Processing fee |
|---|---|---|---|
| ICICI Bank | 3% of outstanding before 24 EMIs; nil after 24 EMIs | 3% if the loan is up to 24 months old, nil after; loans from 1 Jan 2026: any number of times a year, no EMIs need to be paid first | Up to 2% |
| HDFC Bank | 4% up to 24 EMIs; 3% from 25 to 36; 2% after 36 | After the 1st EMI, up to 25% of outstanding, once a financial year and twice in the tenure; same 4%, 3%, 2% on the amount paid | Up to ₹6,500 + GST |
| Axis Bank (loans under ₹10 lakh) | 3% up to 36 EMIs; 2% after; no lock-in | Up to 25% of outstanding a year free after 12 EMIs; otherwise 3% or 2% | Up to 2% + GST |
| Kotak Mahindra Bank | 4% + taxes up to 3 years; 2% + taxes after; no lock-in after the first EMI | Up to 20% of outstanding once a financial year, same charge | Up to 5% + taxes |
| Bajaj Finance (term loan) | Up to 4.72% of outstanding, including taxes | Up to 4.72% of the amount paid, including taxes | Up to 4.13%, including taxes |
| Tata Capital | 6.5% within 12 months of disbursal; 4.5% after | Up to 25% of the disbursed amount free; above that 6.5% or 4.5% | Up to 5% + GST |
| IDFC FIRST Bank (FIRSTmoney standard) | Nil | Not allowed | Zero |
ICICI Bank, Axis Bank, Kotak and Tata Capital quote charges before GST, and HDFC Bank says taxes are added on top. For Axis Bank loans of ₹10 lakh or more closed from your own funds, the charge is 3% before 12 EMIs and nil after. IDFC FIRST Bank's pre-qualified loans allow foreclosure after 12 EMIs at 5% of outstanding (its page also says these can be closed "anytime without any charges", so confirm with the bank). SBI's current Xpress Credit prepayment charge could not be confirmed on SBI's own site on 20 November 2026 (two SBI documents show different figures), so it is left out.
What did RBI change from 1 January 2026?
RBI's Pre-payment Charges on Loans Directions, 2025 (2 July 2025) apply to loans sanctioned or renewed on or after 1 January 2026:
- No pre-payment charge on floating-rate loans to individuals for non-business purposes, for part or full prepayment, from any source of funds, with no minimum lock-in.
- Fixed-rate loans and other cases: charges follow the lender's board-approved policy, and on term loans are levied on the amount prepaid.
- Disclosure: whether a charge applies must be stated in the sanction letter, the loan agreement and the Key Facts Statement. A charge that was not disclosed this way cannot be levied, and a fee the lender waived earlier cannot be charged at prepayment.
- No charge if the lender asks you to prepay.
Most bank and NBFC personal loans are fixed-rate (Axis Bank says so on its fees page), so for a typical personal loan the table above still applies. If your loan is floating-rate and was sanctioned on or after 1 January 2026, ask the lender to confirm in writing that no charge applies.
A worked example: close after 12 EMIs, or keep paying?
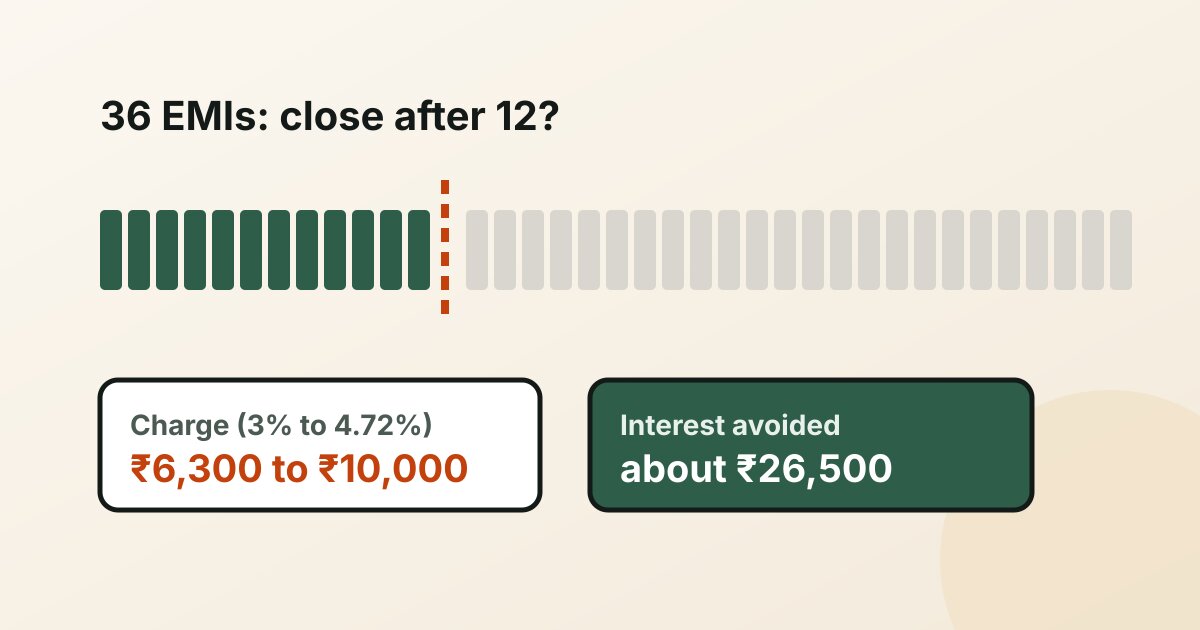
You borrowed ₹3 lakh at 11.60% for 3 years (ICICI Bank's published mean rate for July to September 2026). The EMI is ₹9,907. After 12 EMIs:
| Amount | |
|---|---|
| Principal outstanding | ₹2,11,297 |
| EMIs left (24 × ₹9,907) | ₹2,37,770 |
| Future interest you avoid by closing now | about ₹26,472 |
The charge on ₹2,11,297 outstanding, before GST:
| Charge rate | Charge | Net saving before GST |
|---|---|---|
| 3% (ICICI Bank before 24 EMIs; Axis Bank) | ₹6,339 | about ₹20,100 |
| 4% (HDFC Bank up to 24 EMIs; Kotak) | ₹8,452 | about ₹18,000 |
| 4.5% (Tata Capital after 12 months) | ₹9,508 | about ₹17,000 |
| 4.72% incl. taxes (Bajaj Finance maximum) | ₹9,973 | about ₹16,500 |
GST is then added to the charge where the lender says so, which trims the saving a little but does not change the answer: closing after 12 EMIs saves money at every lender above.
Late in the tenure the answer changes. After 24 EMIs on the same loan, only ₹1,11,740 is outstanding and the remaining 12 EMIs carry about ₹7,145 of interest. At ICICI Bank the charge is now nil, so closing saves the full ₹7,145. At HDFC Bank's 3% (25 to 36 EMIs) the charge is ₹3,352 plus GST, so the saving halves. If only a few EMIs are left, keeping the money as an emergency fund can be the better choice.
Part-payment instead of closing
Say you get a ₹50,000 bonus after the 12th EMI and prepay it, keeping the same EMI. The loan ends 6 months early (in 18 more EMIs instead of 24, the last one smaller) and you save about ₹11,400 in interest. The part-payment charge would be ₹1,500 at 3% or ₹2,000 at 4%, plus GST, where one applies. If you would rather lower the EMI than shorten the tenure, ask the lender: the same prepayment would bring the EMI down from ₹9,907 to about ₹7,563 over the remaining 24 months.
Before you foreclose: a checklist
- Clear costlier debt first. Credit card dues and app loans cost far more than a bank personal loan. Our guide to debt consolidation mistakes explains why leaving the costliest debt out is the most expensive error.
- Ask for the foreclosure statement showing principal, interest to date, the charge and GST, and pay only to the lender's own account.
- Get the closure letter (NOC) and check your credit report shows the loan as "closed", not "settled". Our guide on settled vs closed shows why the status matters.
- Keep an emergency fund. Closing a loan with every rupee you have and then taking an app loan next month undoes the saving.
- Moving to a cheaper lender? Count both costs. A balance transfer closes your old loan early, so the old lender's foreclosure charge applies, plus the new lender's processing fee. Our personal loan balance transfer page works through when a switch pays, and consolidation vs balance transfer vs top-up compares the options.
How AdvanceCred can help
AdvanceCred is a credit advisory and loan intermediation firm in Mumbai. It is not a lender. If you are paying a costly personal loan plus app loans or cards, an advisor can work out whether one loan from a partner bank or NBFC would cost less after the foreclosure charges on what you close. AdvanceCred works on cases with up to 1 payday loan, up to 5 app and personal loans in total and up to 5 credit cards. The lender decides approval, amount, rate and tenure.
Try the loan-merge checker, browse more in the debt consolidation guides hub, or leave your details below.
Sources
- ICICI Bank, Personal loan service charges (foreclosure 3% before 24 EMIs, nil after; part-prepayment rules for loans up to and from 1 January 2026; processing up to 2%; GST extra), checked 20 November 2026: icici.bank.in
- ICICI Bank, Personal loan interest rates (mean 11.60% for July to September 2026), checked 18 November 2026: icici.bank.in
- HDFC Bank, Personal loan interest rates and charges (foreclosure 4%, 3%, 2% by EMIs paid; part-prepayment up to 25% once a year, twice in tenure; processing up to ₹6,500 + GST), checked 20 November 2026: hdfc.bank.in
- Axis Bank, Personal loan interest rates and charges (3% up to 36 EMIs, 2% after; ₹10 lakh and above rule; 25% free part-payment after 12 EMIs; no lock-in; fixed-rate), checked 20 November 2026: axis.bank.in
- Kotak Mahindra Bank, Personal loan fees and charges (4% up to 3 years, 2% after; 20% part-payment once a year; processing up to 5%), checked 20 November 2026: kotak.bank.in
- Bajaj Finance, All fees and charges (term loan foreclosure and part-prepayment up to 4.72% including taxes; processing up to 4.13%), checked 20 November 2026: bajajfinserv.in
- Tata Capital, Personal loan rates and charges (6.5% within 12 months, 4.5% after; 25% of disbursed amount free), checked 20 November 2026: tatacapital.com
- IDFC FIRST Bank, Personal loan fees and charges (FIRSTmoney standard: nil foreclosure, no part-payment, zero processing; pre-qualified: 5% after 12 EMIs), checked 20 November 2026: idfcfirst.bank.in
- Reserve Bank of India, Pre-payment Charges on Loans Directions, 2025, RBI/2025-26/64, 2 July 2025 (paras 3, 5, 6, 8, 9, 10), checked 20 November 2026: rbi.org.in
- EMI, balance and interest figures: standard reducing-balance formula, calculated by AdvanceCred, 20 November 2026.