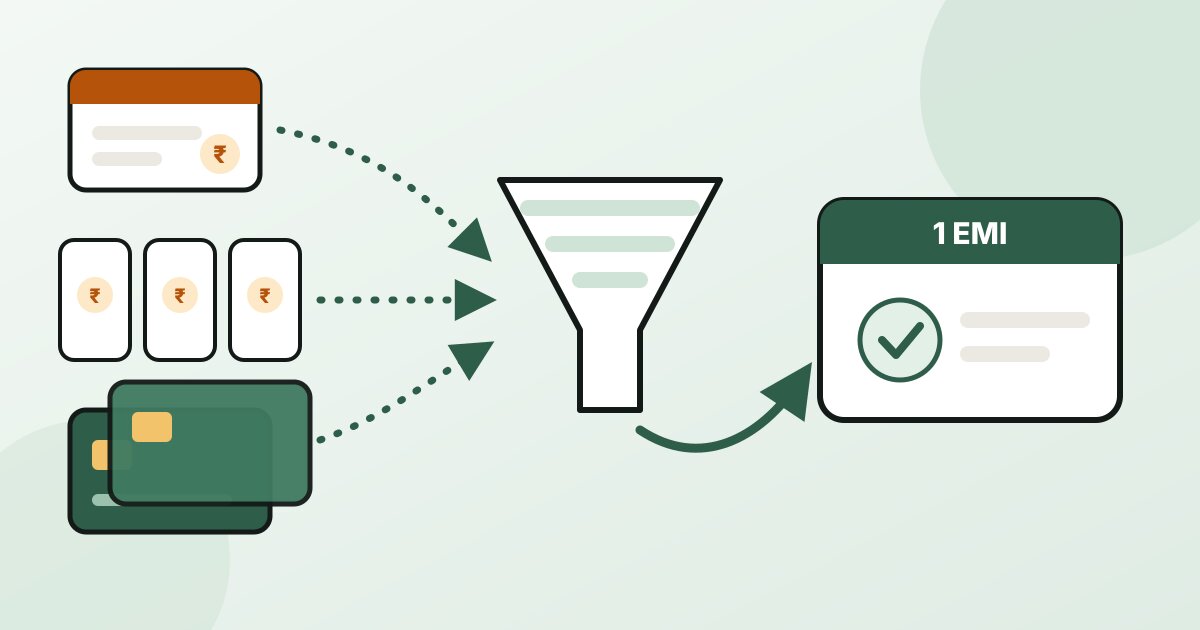
Short answer: no RBI rule caps how many loans you can merge into one. The limit is set by the lender: the one new EMI has to fit within the share of your salary that lenders allow for EMIs, and your credit report has to show you can carry it. AdvanceCred works on cases with up to 1 payday loan, up to 5 app loans and personal loans in total, and up to 5 credit cards. The lender still decides approval, amount, rate and tenure.
This article is part of our series on getting out of multiple loans. If you are deciding whether you need to merge at all, read the six warning signs first. To try your own numbers, use the loan consolidation calculator.
Is there a limit on how many loans can be merged?
There is no fixed number in RBI's rules. Merging (consolidating) simply means taking one new loan that pays off several old ones, so the question a lender asks is not "how many loans?" but "can this person repay the one new loan?" Two things decide that: how much of your salary already goes to EMIs, and what your credit report shows.
The number of loans matters indirectly. More loans usually means a bigger amount to clear, more enquiries on your report and more chance that one of them is already late. That is why advisors and lenders set practical limits.
What AdvanceCred can merge
| Type of debt | AdvanceCred's case limit | Notes |
|---|---|---|
| Payday loan (repaid in one go on payday) | Up to 1 | The most expensive and the hardest for banks to accept in numbers |
| App loans and personal loans | Up to 5 in total | Counted together, whether from an app, an NBFC or a bank |
| Credit cards | Up to 5 | Outstanding dues, not just the minimum due |
| Home loan, car loan, gold loan | Not part of an unsecured merge | Secured loans have their own terms; usually best left alone |
These are AdvanceCred's own limits for the cases its advisors take on. A case within them is not guaranteed approval: the bank or NBFC checks your income, existing obligations and credit history and makes its own decision.
Why each extra loan makes a merge harder
- The new EMI has to fit your FOIR. FOIR (fixed obligations to income ratio) is all your monthly EMIs divided by your monthly income. Kotak Mahindra Bank says lenders prefer a FOIR of 40% to 50%. The new loan's EMI, plus anything you keep (a home or car loan EMI), has to fit inside that.
- Every loan is on your credit report quickly. Since 1 January 2025, RBI has required lenders to report credit information to credit bureaus every fortnight. Three app loans taken in the same month show up together, and TransUnion CIBIL notes that many applications in a short period can make lenders see you as a riskier borrower.
- Small loans add up. Five app loans of ₹20,000 to ₹40,000 each can mean ₹1.5 lakh or more to clear, plus any foreclosure charges in each loan's terms. The new loan has to cover all of it, plus its own processing fee.
- One late payment changes the case. A single missed EMI on any of the loans can be the reason a bank says no. The more loans you have, the more due dates there are to miss.
Worked example: five debts, one EMI
Take-home salary ₹60,000. The amounts and EMIs below are an example to show the arithmetic; use the figures from your own loan statements.
| Debt | Still owed | Paid each month |
|---|---|---|
| Payday loan | ₹16,500 (₹15,000 plus assumed charges) | Due in one go on payday |
| App loan 1 | ₹30,000 | ₹6,000 |
| App loan 2 | ₹25,000 | ₹5,000 |
| App loan 3 | ₹35,000 | ₹7,000 |
| Personal loan | ₹2,00,000 | ₹6,600 |
| Two credit cards | ₹78,500 | ₹6,000 |
| Total | ₹3,85,000 | ₹30,600 a month, plus ₹16,500 on payday |
Is it within the limits? Yes: 1 payday loan, 4 app and personal loans (limit 5), 2 cards (limit 5).
What it costs today: ₹30,600 is 51% of a ₹60,000 salary, already at the top of the 40% to 50% range. In the month the payday loan is due, ₹47,100 leaves the account, which is 78.5% of the salary. That is the month people take the next app loan.
One loan instead: a ₹3.85 lakh personal loan at ICICI Bank's published mean rate of 11.60% a year:
| Tenure | EMI | Share of ₹60,000 salary | Total interest |
|---|---|---|---|
| 3 years | about ₹12,714 | 21% | about ₹72,700 |
| 5 years | about ₹8,486 | 14% | about ₹1,24,160 |
| 5 years at 16.50% (top of ICICI's range) | about ₹9,465 | 16% | about ₹1,82,900 |
The catch: the 5-year loan more than halves the monthly outgo, but it carries more total interest than the 3-year one. The processing fee at ICICI Bank is up to 2% plus taxes, about ₹9,086 on ₹3.85 lakh at 18% GST. If you can afford the 3-year EMI, it costs less overall. And the merge only works if you do not take new app loans afterwards.
Too many loans to merge? What to do
If you have, say, 2 payday loans and 6 app loans, the case is outside AdvanceCred's limits and most banks will hesitate too. Here is what usually helps, in this order:
- Stop new borrowing today. Every new app loan moves you further from a merge. Uninstalling the apps helps more than it sounds.
- Reduce the count, smallest first. Repay the smallest app loans or the payday loan from a salary advance, a bonus or savings. Closing two small loans can bring you within the limits faster than paying a little on all of them.
- Keep every remaining EMI on time, even if you pay only the smaller ones in full and talk to the lender about the rest. A clean last few months matters more to a bank than an old mistake.
- Ask a lender for a written plan before you miss a due date. A short restructured plan agreed in advance is better than a missed EMI, which is reported within weeks.
- Consider a co-applicant, such as a spouse with income. A combined income can bring the FOIR down.
- If you own a house or flat, a loan against property can clear several debts at a lower rate. The property is mortgaged and can be at risk if EMIs are missed, and the lender values the property and decides the amount; valuation, legal and processing charges apply.
Do not pay anyone who promises to "remove" loans from your credit report or to merge any number of loans with "guaranteed" approval. No advisor can promise that, and a settled loan stays on your report as settled.
Which loans should you merge first?
Merge the expensive ones: the payday loan, then app loans, then credit card dues, then small personal loans. Keep cheaper secured loans as they are. If you have a mix of app loans and card dues, see how to pay off multiple payday and app loans and how to merge multiple EMIs into one. For card dues on their own, see credit card EMI consolidation. For a full comparison of one consolidation loan with a balance transfer or top-up, read debt consolidation loan vs balance transfer vs top-up.
If a payday loan is how the problem started, read why you should never take a payday loan before taking another.
How AdvanceCred can help
AdvanceCred is a credit advisory and loan intermediation firm based in Mumbai. It is not a lender. An advisor goes through each of your loans and cards with you, checks whether the case is within the limits above, and compares one-loan options from partner banks and NBFCs on a debt consolidation loan. The lender decides approval, amount, rate and tenure. Check your loans on the calculator, or leave your details in the short form below and an advisor will call you.
Sources
Checked between 31 October and 2 November 2026 as dated below. The loan amounts, EMIs and payday charges in the example are assumptions for illustration; the EMIs, shares of salary and totals are AdvanceCred's own arithmetic. AdvanceCred's case limits are its own policy (set 30 October 2026).
- ICICI Bank, Personal loan interest rates (9.99% to 16.50% p.a.; mean 11.60% for July to September 2026; processing fee up to 2% plus taxes), checked 1 November 2026: icici.bank.in
- Kotak Mahindra Bank, "What is FOIR in banking?" ("Lenders prefer a FOIR in the range of 40-50%"), checked 31 October 2026: kotak.bank.in
- Reserve Bank of India, Frequency of reporting of credit information by credit institutions to CICs, RBI/2024-25/60, 8 August 2024 (fortnightly from 1 January 2025): rbi.org.in
- TransUnion CIBIL, "Some of the common credit mistakes to avoid" (multiple applications in a short period), checked 31 October 2026: cibil.com